BUILDING YOUR FUTURE


20+ Years In the industry

Superior experience through fast response times, Exceeding service expectations and,

Keeping our clients best interest in the forefront.

GET STARTED

BUILDING YOUR FUTURE


Nate Atkin - Mortgage Agent

20 Years In the industry

Superior experience through fast response times, Exceeding service expectations and,

Keeping our clients best interest in the forefront.

GET STARTED

Finding the best mortgage can be frustrating.

It doesn't have to be when you follow my 3 step plan.
Get started right away

The best place to start is to connect with me directly. My commitment is to listen to your needs, assess your financial situation, provide professional mortgage advice, and guide you through the mortgage process.
Get clarity

Sorting through all the different mortgage lenders, rates, terms, and features can be overwhelming. Let me cut through the noise. I'll outline the best mortgage products available with your needs in mind.
Proceed with confidence

My goal is to make sure you know exactly where you stand at all times. From your initial application through your mortgage renewal, I'm available to answer any questions and move you along with speed! I've got you covered.

What Our Clients Are Saying

120+ Google Reviews

Services

Whether you're a first-time buyer or an experienced homeowner, our brokerage offers access to some of the best products and rates on the market.

        Renewals

Before renewing with your current lender, let a mortgage professional shop around for you. You'll be amazed at what they can do!

First Time Home Buyers

We help countless first-time buyers get their first mortgage. Our process makes it easy for you to achieve your goal of home ownership. Book a call with us today to learn how.

Competitive Rates

Our rates are consistently competitive, and we take pride in ensuring you receive the best possible rate available.

Referral

We can connect you with expert professionals you may need during the home buying process, including realtors, lawyers, and insurance brokers.

Refinance

Refinancing is a great way to access your home equity for consolidating debt, making home improvements, investing, covering college expenses, and more.

BOOK A CALL

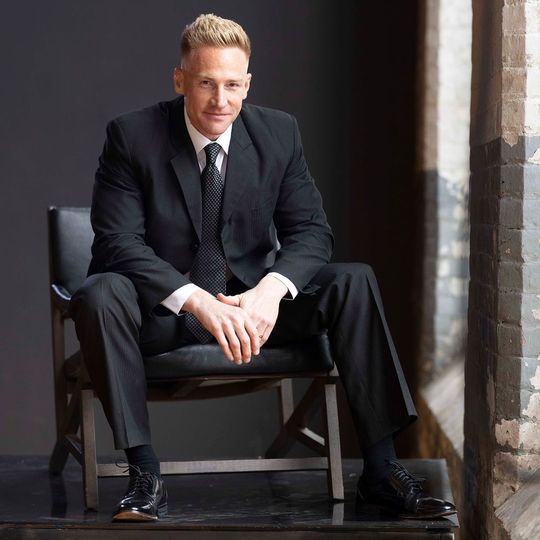
Nate Atkin

Mortgage Agent Level 2

Email Us

License #M24001359

BRX Mortgages | FSRA No. 13463

What we stand for at Hummingbird Mortgages?

We are driven by a passion for helping you navigate life without financial stress. Our goal is to work with you to ensure you have the cash flow and financial security you need during major life milestones. Whether you're buying your first home, helping pay for your kids' weddings or college tuition, taking your dream vacation, getting a new car, investing, or planning for retirement, we are always here to support you.


We bring over 
20 years of proven experience in real estate and mortgage expertise. At Hummingbird Mortgages, a proud member of the BRX Brokerage Group, we have access to over 120 lending partners.


Our focus is to provide you with expert advice and the best mortgage solutions tailored to your unique financial situation.


Our mission
 is to represent you in obtaining the best products, rates, and services, all while offering a superior experience through quick response times, exceeding service expectations, and keeping your best interests at the forefront.


We’re here to assist with all your financing needs, including mortgages, renewals, refinancing, repositioning, HELOCs, private lending, bridge loans, commercial funding, first-time buyers, reverse mortgages, and more.

Additionally, Nate Atkin is the Principal Partner and Managing Agent for a US-based real estate investment group that offers clients the opportunity to invest in multifamily properties on a passive basis. We offer US Mortgage Solutions for Canadians. We also serve both accredited and non-accredited investors, providing a pathway to build wealth through large-scale multifamily assets. With expertise in acquiring and repositioning properties, our team focuses on generating passive income for investors and returning capital upon achieving our business objectives.

(For more information, click on our "US Investing" link.)


We look forward to connecting with you!


Nate & the Hummingbird Mortgages Team

We work with over 120 lenders, including some names you might recognize.

Here are a few:
Everything you need, all in one place

As trusted mortgage providers, let us help you with these services.

Click through any of the services to learn more

Go ahead and schedule a meeting with us

Get started by completing our online mortgage application.

APPLY NOW

We'll let you know exactly where you stand so you can proceed with confidence.

Mortgage articles to keep you informed.

By Hummingbird Mortgages • November 4, 2026
What Lenders Mean by “Good Credit” When You Apply for a Mortgage Credit is simply the ability to borrow money today based on the trust that you’ll repay it in the future. When you apply for a mortgage, lenders want proof that you’ve consistently honoured that trust by managing credit responsibly. But what does a good credit history actually look like to a lender? The 2 / 2 / 2 Rule Explained If you’re newer to credit or want a simple way to remember minimum mortgage credit requirements, think of the 2 / 2 / 2 rule: 2 active trade lines Established for at least 2 years With a minimum combined limit of $2,000 This is a common baseline lenders use when assessing credit for mortgage financing. What Counts as a Trade Line? A trade line is any account where credit is extended to you, such as: A credit card A line of credit A car loan A personal or installment loan Each trade line reports your payment history to the credit bureau and contributes to your credit score. For a trade line to be considered active , it must: Have been used at least once, and Show activity at least once every three months Why Time Matters Lenders want to see that you’ve managed credit responsibly over time , not just recently. Using two trade lines consistently for at least two years helps demonstrate stable financial habits and reliability. Understanding Credit Limits vs. Balances The credit limit is what matters—not the balance. For example: A $1,000 credit card + a $2,500 line of credit = $3,500 total limit This meets the minimum requirement You do not need to carry a balance to build credit. In fact, the best approach is to: Use your credit regularly Pay it off in full each month (for credit cards) Make all loan payments on time If your lender offers a credit limit increase and you’re managing credit well, it’s often a good idea to accept it. Higher limits—used responsibly—can strengthen your credit profile. A Simple Way to Build Credit Automatically One effective strategy is to: Put recurring bills on your credit card Set up an automatic transfer to pay the balance in full every month Automation helps build positive credit history without requiring constant attention—just be sure to monitor your accounts to ensure everything runs smoothly. What About Credit Scores? Yes, credit scores matter—but they’re not the whole story. If you: Have two active trade lines Established for two years With at least $2,000 in total limits And no missed payments …your credit score will generally take care of itself. That said, it’s still wise to review your credit report occasionally to check for errors or unfamiliar accounts. Final Thoughts If you’re thinking about buying a home in the next couple of years, now is the perfect time to review your credit and make sure you’re on track. Small adjustments today can make a big difference when it’s time to apply for a mortgage. If you’d like help reviewing your credit or understanding how it affects your mortgage options, feel free to connect anytime. I’d be happy to walk through it with you and help you plan with confidence.
By Hummingbird Mortgages • October 28, 2026
On October 28, 2026, the Bank of Canada raised its key interest rate by 0.25%, bringing it to 2.5%. If you have a mortgage, are shopping for a home, or have a renewal coming up, this decision matters. Here is a plain-language look at what changed, why it happened, and what it could mean for you.
By Hummingbird Mortgages • October 21, 2026
Can’t Find the Right Home After You’re Pre-Approved? There’s Another Option The best place to start any home purchase is with a mortgage pre-approval. It gives you clarity around your budget and lets you shop with confidence. But what happens when you’ve been pre-approved, you know where you want to live—and nothing suitable fits your price range? This is a common challenge, especially for first-time homebuyers. Before buyer fatigue sets in, it may be worth considering a different approach: buying a home that needs work and financing the renovations as part of your mortgage . What Is a Purchase Plus Improvements Mortgage? A purchase plus improvements program allows you to buy a property and include the cost of approved renovations directly in your mortgage. This can be a great solution if: You can’t find a move-in-ready home within budget You’re open to renovations You want to customize the home from the start It opens up more options and can help you get into a location or property that would otherwise be out of reach. How the Process Works While the idea is straightforward, the process itself is structured and requires planning. Here’s a high-level overview: Renovation quotes are required upfront You’ll need detailed quotes for the work you want completed before final mortgage approval. Renovations must add value The lender must be satisfied that the improvements will increase the property’s value accordingly. Funds are reimbursed, not advanced You pay for the renovations initially. Once the work is completed and verified by an appraiser, the lender reimburses you and adds the cost to your mortgage. With the right guidance, this process is very manageable—but it’s important to understand the steps before committing. Is This Program Right for You? Purchase plus improvements isn’t for everyone. Buying a home is already a big undertaking, and adding renovations can increase stress—especially if timelines, budgets, or contractors become challenging. That said, if you’re financially prepared and like the idea of shaping the home to fit your needs, this program can be an excellent way to get more value and flexibility from your purchase. Final Thoughts If you’re struggling to find the right home after being pre-approved, you may not need to lower your expectations—you may just need a different strategy. If you’d like to explore whether a purchase plus improvements mortgage makes sense for you, feel free to connect. I’d be happy to walk you through the process and outline exactly what this option would look like in your situation.
By Hummingbird Mortgages • November 4, 2026
What Lenders Mean by “Good Credit” When You Apply for a Mortgage Credit is simply the ability to borrow money today based on the trust that you’ll repay it in the future. When you apply for a mortgage, lenders want proof that you’ve consistently honoured that trust by managing credit responsibly. But what does a good credit history actually look like to a lender? The 2 / 2 / 2 Rule Explained If you’re newer to credit or want a simple way to remember minimum mortgage credit requirements, think of the 2 / 2 / 2 rule: 2 active trade lines Established for at least 2 years With a minimum combined limit of $2,000 This is a common baseline lenders use when assessing credit for mortgage financing. What Counts as a Trade Line? A trade line is any account where credit is extended to you, such as: A credit card A line of credit A car loan A personal or installment loan Each trade line reports your payment history to the credit bureau and contributes to your credit score. For a trade line to be considered active , it must: Have been used at least once, and Show activity at least once every three months Why Time Matters Lenders want to see that you’ve managed credit responsibly over time , not just recently. Using two trade lines consistently for at least two years helps demonstrate stable financial habits and reliability. Understanding Credit Limits vs. Balances The credit limit is what matters—not the balance. For example: A $1,000 credit card + a $2,500 line of credit = $3,500 total limit This meets the minimum requirement You do not need to carry a balance to build credit. In fact, the best approach is to: Use your credit regularly Pay it off in full each month (for credit cards) Make all loan payments on time If your lender offers a credit limit increase and you’re managing credit well, it’s often a good idea to accept it. Higher limits—used responsibly—can strengthen your credit profile. A Simple Way to Build Credit Automatically One effective strategy is to: Put recurring bills on your credit card Set up an automatic transfer to pay the balance in full every month Automation helps build positive credit history without requiring constant attention—just be sure to monitor your accounts to ensure everything runs smoothly. What About Credit Scores? Yes, credit scores matter—but they’re not the whole story. If you: Have two active trade lines Established for two years With at least $2,000 in total limits And no missed payments …your credit score will generally take care of itself. That said, it’s still wise to review your credit report occasionally to check for errors or unfamiliar accounts. Final Thoughts If you’re thinking about buying a home in the next couple of years, now is the perfect time to review your credit and make sure you’re on track. Small adjustments today can make a big difference when it’s time to apply for a mortgage. If you’d like help reviewing your credit or understanding how it affects your mortgage options, feel free to connect anytime. I’d be happy to walk through it with you and help you plan with confidence.
By Hummingbird Mortgages • October 28, 2026
On October 28, 2026, the Bank of Canada raised its key interest rate by 0.25%, bringing it to 2.5%. If you have a mortgage, are shopping for a home, or have a renewal coming up, this decision matters. Here is a plain-language look at what changed, why it happened, and what it could mean for you.
By Hummingbird Mortgages • October 21, 2026
Can’t Find the Right Home After You’re Pre-Approved? There’s Another Option The best place to start any home purchase is with a mortgage pre-approval. It gives you clarity around your budget and lets you shop with confidence. But what happens when you’ve been pre-approved, you know where you want to live—and nothing suitable fits your price range? This is a common challenge, especially for first-time homebuyers. Before buyer fatigue sets in, it may be worth considering a different approach: buying a home that needs work and financing the renovations as part of your mortgage . What Is a Purchase Plus Improvements Mortgage? A purchase plus improvements program allows you to buy a property and include the cost of approved renovations directly in your mortgage. This can be a great solution if: You can’t find a move-in-ready home within budget You’re open to renovations You want to customize the home from the start It opens up more options and can help you get into a location or property that would otherwise be out of reach. How the Process Works While the idea is straightforward, the process itself is structured and requires planning. Here’s a high-level overview: Renovation quotes are required upfront You’ll need detailed quotes for the work you want completed before final mortgage approval. Renovations must add value The lender must be satisfied that the improvements will increase the property’s value accordingly. Funds are reimbursed, not advanced You pay for the renovations initially. Once the work is completed and verified by an appraiser, the lender reimburses you and adds the cost to your mortgage. With the right guidance, this process is very manageable—but it’s important to understand the steps before committing. Is This Program Right for You? Purchase plus improvements isn’t for everyone. Buying a home is already a big undertaking, and adding renovations can increase stress—especially if timelines, budgets, or contractors become challenging. That said, if you’re financially prepared and like the idea of shaping the home to fit your needs, this program can be an excellent way to get more value and flexibility from your purchase. Final Thoughts If you’re struggling to find the right home after being pre-approved, you may not need to lower your expectations—you may just need a different strategy. If you’d like to explore whether a purchase plus improvements mortgage makes sense for you, feel free to connect. I’d be happy to walk you through the process and outline exactly what this option would look like in your situation.
Show More